Economy
Blue States Are Changing The Rules For The Rich — But It’ll Cost ALL Of US

Every politician eventually runs out of other people’s money to spend. Blue state governors and legislators are just running out faster than the rest.
Right now, there is a coordinated wave of new tax proposals sweeping California, New York, Washington state, Massachusetts, Michigan and Connecticut. The common thread? They all believe the solution to self-inflicted budget crises is to reach deeper into the pockets of their most productive residents. And if those residents decide to leave, they want to charge them an exit tax on the way out. What? Is this America?
Let that sink in. An exit tax. As in, we know you’re leaving because of our lousy tax structure, and we want the door to hit you on the way out.
The proposals on the table right now
California’s Billionaire Tax Act is the crown jewel of this movement. The ballot measure would impose a one-time 5% tax on the total net worth of anyone worth more than $1 billion residing in the state. Not their income. Their net worth. Think about what that means for a founder whose entire net worth is locked up in a private company that employs thousands of people. And think about how many millionaires they made themselves building that company. You could have $2 million in liquid assets, and a $100 billion paper valuation and California would hand you a $5 billion tax bill. That’s not a tax policy. That’s an asset seizure dressed up as fairness.
Washington state, which has never had an income tax in its history just passed a 9.9% tax on incomes over $1 million. The moment that bill cleared the legislature, Starbucks founder Howard Schultz announced he was moving to Florida. Shocker. Starbucks’ own headquarters announced it’s moving to Tennessee. Shocker. When the founder and the company both leave at the same time, that’s not a coincidence. That’s a message we hear in a resounding fashion from high tax high spend states.
Michigan wants to amend its state constitution to impose a 9.25% top rate on incomes over $500,000. For residents of Detroit, the combined state and local rate would approach nearly 12%. Meanwhile, across the border in Ohio, the flat income tax rate is 2.75%. In Indiana, it’s 2.95%. You don’t need to be a certified financial planner to do that math. You just need a moving truck.
I want to be clear about something. I’m not here to defend billionaires. I’m here to defend economic reality.
The top 1% of California taxpayers currently supplies nearly half of all income tax collections in the state. Half. That’s not a sustainable revenue model. That’s a house of cards. And the moment those top earners which are not just the billionaires, but when the $500,000-a-year business owners, the startup investors, the executives start relocating, the math collapses for everyone else who stays behind.
This has already started. Six of California’s 214 billionaires left before the proposed January 1, 2026, residency cutoff. Those six people alone took $27 billion in potential tax revenue with them. Google co-founder Larry Page dropped $170 million on a Miami estate and moved his family office out of California. David Sacks who lived 30 years in the state packed up for Texas and called the proposed tax what it really is which is an asset seizure.
Here’s what I’ve learned in over thirty years as a financial advisor. Wealthy people don’t wait for the bill to arrive. They plan years in advance. The exits happening today were decided in law offices and financial planning meetings 18 months ago. The exits that haven’t happened yet are being decided right now.
Why this should matter to you even if you’re not a billionaire
Here’s where this stops being an abstract policy debate and starts affecting your daily life.
When high earners leave a state, the remaining tax base must pick up the tab. Services get cut. Or taxes get raised on the next rung of earners which are the people making $150,000, then $100,000, then lower. California, New York, and Michigan didn’t build world-class universities, hospitals, and infrastructure by accident. They built them on the backs of a thriving private economy. Dismantle the engine, and eventually the whole train stops.
There’s also a broader economic signal being sent here. When Washington state is no longer a zero-income-tax state, when California makes it financially dangerous to be a successful founder, and when Michigan punishes its highest earners at nearly 12 cents on the dollar innovation, capital, and job creation go somewhere else. And somewhere else, right now, is Florida, Texas, Tennessee, and Nevada.
What you should do right now
If you live in one of these states and you have built meaningful wealth including a business, a portfolio, a real estate holding, or a qualified retirement account this is not a news story to skim and forget. This is a planning conversation to have with your financial advisor and your estate planning attorney. Several of these proposals include exit taxes on residents who leave within five years of implementation. The window to plan proactively is now. Not after the ballot measure passes. Not after the bill is signed. Now.
Wealthy people are not a fixed resource. They are mobile, they are organized, and they have options.
And right now, those options are looking a lot like the Sunshine State instead of the Golden State.
Oil prices took a sharp turn Monday, tumbling to their lowest levels in 11 days as traders reacted to signs of possible diplomatic movement between the United States and Iran — while Saudi Arabia finds new ways to keep massive amounts of crude flowing despite mounting turmoil across the Middle East.
Brent crude for November plunged $2.69, or 2.6%, to $101.18 a barrel by 12:54 p.m. GMT after briefly touching its lowest level since September 10.
U.S. crude fell even harder.
West Texas Intermediate’s October contract, which expires Tuesday, dropped $2.69, or 2.7%, to $97.61 a barrel. The November WTI contract stood at $93.49.
The sudden retreat came despite continued fighting across the Middle East and another exchange of threats between Washington and Tehran over the weekend.
But markets received a potentially significant signal Sunday.
President Donald Trump said he would be open to meeting Iranian President Masoud Pezeshkian, who is expected to travel to New York for this week’s United Nations General Assembly.
Iran has also reportedly conveyed conditions to mediators for potentially reopening negotiations, according to a report citing Iranian security chief Mohsen Rezaei.
Those signals raised the possibility of renewed talks between Washington and Tehran, reducing some of the immediate fears that further escalation could threaten global energy supplies.
But on the ground, the situation remains volatile.
Iran-backed Houthi forces in Yemen said they attacked Riyadh and a Saudi Aramco facility in the Red Sea city of Yanbu while continuing efforts to expand their control in Yemen.
China has also pressed Iran to help restrain the Houthis following an appeal from Saudi Arabia, according to sources familiar with the discussions.
Meanwhile, Saudi Arabia is making major adjustments to keep its oil moving.
Attacks disrupted the kingdom’s East-West pipeline and complicated shipments through Yanbu, but Saudi Aramco has responded by increasing exports through the Strait of Hormuz this month and next.
That shift appears to be having a significant impact on global supply concerns.
“Middle East oil flows remain surprisingly strong despite the disruption to Saudi Arabia’s East-West pipeline,” JPMorgan analysts said in a September 18 note.
The numbers behind the shift are dramatic.
“The most notable pivot has come from Saudi Arabia,” the analysts said, as satellite data indicated Saudi oil moving through the Strait of Hormuz averaged 2.9 million barrels per day over the previous six days.
In August, that figure had been just 700,000 barrels per day.
That massive increase has helped ease immediate fears that the escalating conflict could trigger a much more serious supply crunch.
Oil producers are also increasingly turning to ship-to-ship transfers near Oman to keep crude moving through the region.
Those workarounds have helped prevent a more severe disruption in global supplies, but they aren’t coming cheaply.
Shipping costs have surged as tankers navigate increasingly complicated and potentially dangerous routes.
There are supply concerns elsewhere as well.
Libya’s National Oil Corporation said production at the country’s Sharara oilfield had been partially reduced, although officials did not provide a reason for the reduction.
Monday’s selloff leaves Brent hovering just above the closely watched $100-per-barrel threshold after prices surged above $108 last week.
That puts global oil markets at a critical point.
On one side, continued fighting, attacks on energy infrastructure and disrupted shipping routes are keeping geopolitical risk elevated.
On the other, Saudi Arabia’s ability to reroute enormous quantities of crude — combined with the possibility of renewed diplomacy between Washington and Tehran — is easing fears of an immediate supply shock.
Now traders are turning their attention to New York.
This week’s United Nations meetings could provide the next major signal about whether Washington and Tehran are moving toward negotiations or whether tensions will escalate again.
At the same time, Saudi Arabia is racing to keep crude flowing through one of the world’s most strategically important — and increasingly volatile — energy corridors.
With Brent sitting barely above $100, either development could quickly send oil markets moving again.
An extraordinary era in American business is coming to an end.
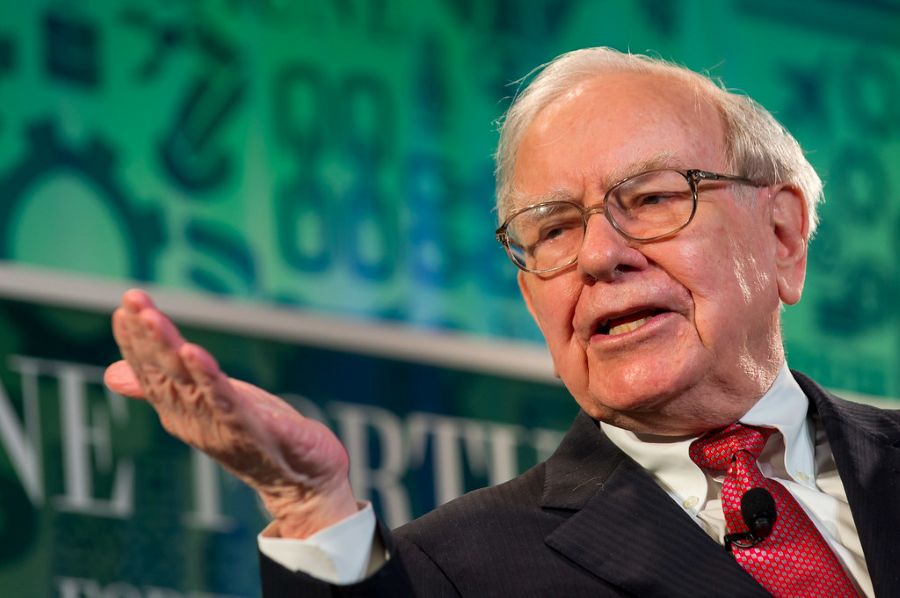
Warren Buffett is officially stepping away from the chairman’s seat at Berkshire Hathaway, closing another chapter in a remarkable run that stretched for more than half a century and turned the legendary investor into one of the most influential figures in modern business.
Berkshire announced Friday that Buffett, 96, will become chairman emeritus effective immediately. He isn’t cutting ties with the company entirely, however, and will remain on Berkshire’s board of directors.
Taking his place as chairman will be his son, Howard Buffett.
Howard has served as a Berkshire director since 1993 and has spent decades leading the Howard G. Buffett Foundation. His elevation to chairman represents another major piece of a succession plan Berkshire has been preparing for years.
For Warren Buffett, the announcement marks the latest — and one of the most significant — steps away from the company he spent decades building into a corporate powerhouse.
Buffett had served as Berkshire Hathaway’s chairman since 1970.
During that time, he oversaw an extraordinary transformation, taking what had once been a struggling textile business and building it into a massive conglomerate with operations spanning insurance, railroads, energy, manufacturing, retail and services.
His influence over the company’s day-to-day operations had already begun to diminish.
Buffett stepped down as Berkshire’s chief executive late last year, turning control of the company over to longtime lieutenant Greg Abel.
Now the chairman’s title is changing hands as well.
Friday’s announcement means Berkshire is entering a new era in which Abel runs the company’s operations while Howard Buffett oversees the board.
Warren Buffett, however, isn’t disappearing.
As chairman emeritus, he will remain a director and continue providing his judgment and perspective to the company’s leadership — preserving a connection between Berkshire’s future and the man who shaped its identity for generations.
Following the announcement, Abel paid tribute to the enormous impact Buffett has had on the company.
“Warren’s impact on Berkshire and its owners is without parallel in the history of American business,” Abel said in a statement. “The culture Warren built and the values he championed will remain at the heart of Berkshire, and Howard will be their guardian.”
That culture became almost as famous as Buffett himself.
Rather than chasing every new market trend, Buffett built his reputation around patience, long-term investing, disciplined acquisitions and a straightforward approach to evaluating businesses.
Under his leadership, Berkshire accumulated an enormous portfolio of operating companies while also becoming famous for taking major stock positions in some of America’s most recognizable corporations.
Along the way, Buffett became more than a corporate executive.
His annual shareholder letters, public appearances and Berkshire shareholder meetings turned the Omaha investor into one of the world’s most closely followed voices on investing, business and the American economy.
But the transition away from Buffett has been unfolding for some time.
Last year, Buffett announced that Abel would become Berkshire’s top executive. He later signaled that his own public presence would shrink, including fewer appearances at Berkshire’s annual meeting and an end to writing the company’s annual shareholder letter.
Howard Buffett’s move into the chairman’s position wasn’t unexpected either.
The younger Buffett had long been identified as an important part of Berkshire’s eventual succession structure, with his father previously describing the chairman’s role as a safeguard for the company’s distinctive culture and values once he was no longer overseeing daily operations.
That succession plan is now becoming reality.
Greg Abel is running Berkshire as CEO.
Howard Buffett is taking control of the board as chairman.
And Warren Buffett — after more than five decades at the center of one of the most remarkable corporate transformations in American history — is moving into an advisory role as chairman emeritus.
The legendary investor may still have a seat at the table.
But the company he built is officially moving into its post-Buffett leadership era.
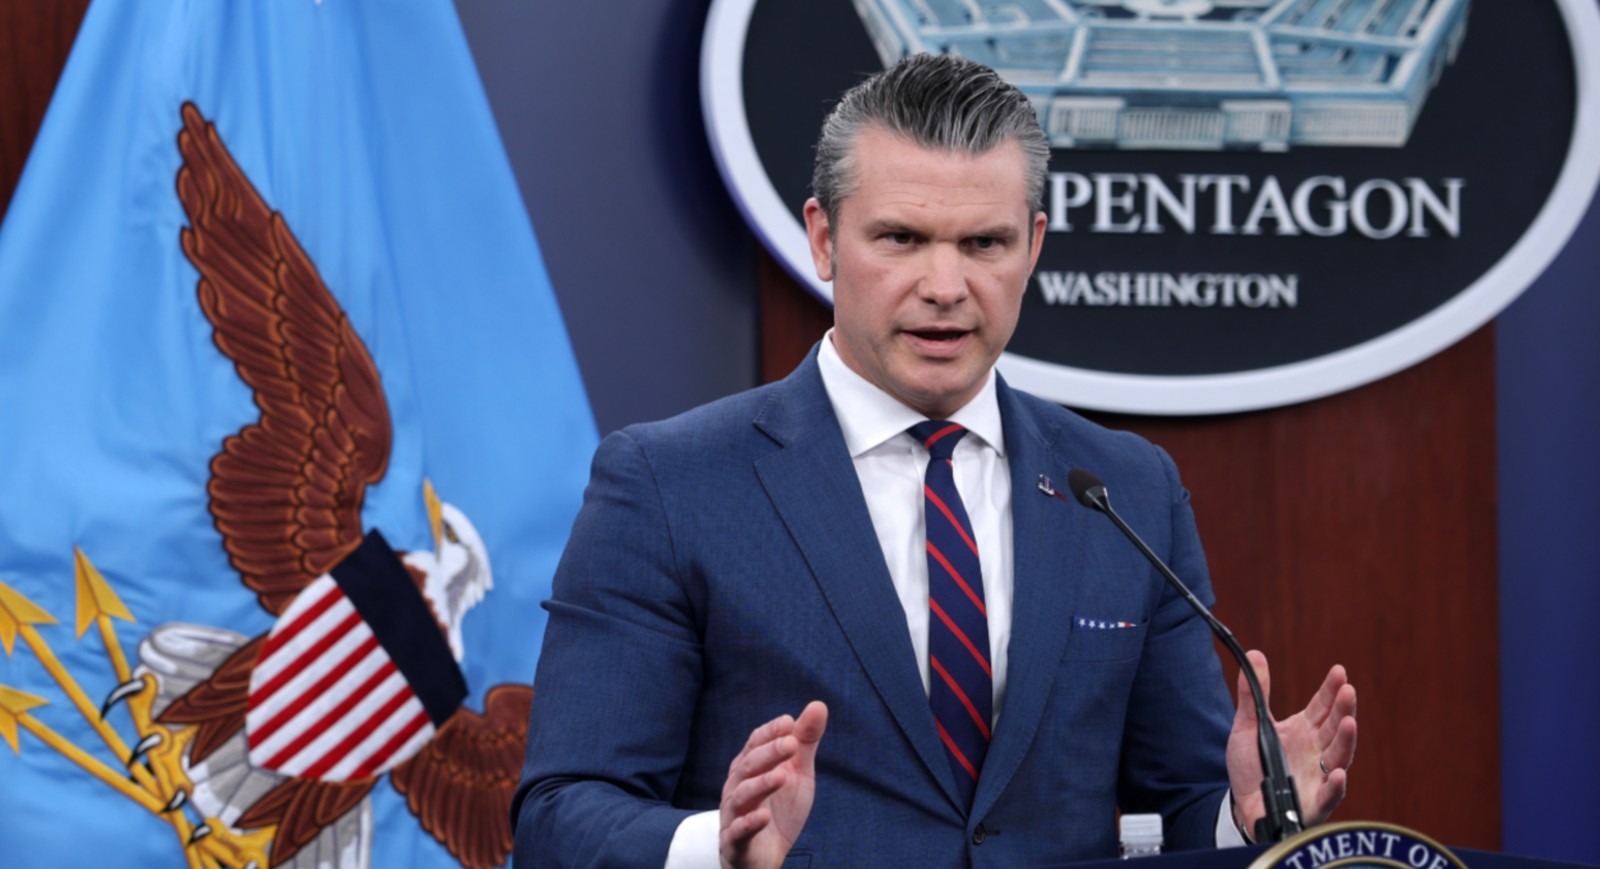
A tragic accident at Edwards Air Force Base claimed the lives of eight Americans Monday when a U.S. Air Force B-52 Stratofortress bomber crashed shortly after takeoff during a routine test mission, according to military officials.
The aircraft went down at approximately 11:20 a.m. PDT while conducting a local test sortie connected to a radar modernization program. Witnesses reported seeing the bomber erupt in flames before a massive plume of black smoke rose into the sky above the Mojave Desert.
Emergency response teams rushed to the scene, but officials quickly determined that there were no survivors.
Speaking at a press conference, Col. James Hayes, deputy commander of the 412th Test Wing, confirmed the devastating loss.
“Today, Edwards Air Force Base experienced a horrible tragedy, and we lost eight great Americans,” Hayes said.
“This crash is deemed to be unsurvivable, and right now, our thoughts and prayers are with the families of those who lost their loved ones,” Hayes added.
Hayes also provided additional details regarding the mission.
“It was a B-52 that was on initial takeoff supporting the radar modernization program, which is a test; it was a local test sortie,” he explained.
According to officials, the crew included military personnel, civilian government employees, and contractors working on the modernization effort. Two Boeing employees were reportedly among those aboard the aircraft.
The loss sent shockwaves through the military community and prompted an outpouring of condolences from government leaders and defense officials across the country.
Defense Secretary Pete Hegseth responded on social media shortly after news of the crash became public.
“May GOD shepherd the souls of these incredible Americans — and watch over their families,” Hegseth wrote.
“Our thoughts and prayers are with the families and unit members at this time. More information will be released as it becomes available,” Hegseth added.
Air Force Secretary Troy Meink also expressed his sorrow over the tragedy.
“We mourn this loss and honor the service of our Airmen, civilians, and contractors who work every day to advance our mission,” Meink said. “My thoughts are with the bomber and test communities during this difficult time.”
The B-52 Stratofortress remains one of the most recognizable aircraft in American military history. First entering service in the 1950s, the bomber has served through multiple conflicts and remains a key component of America’s strategic deterrent capabilities. Despite its age, the aircraft continues to undergo modernization efforts intended to keep it operational for decades to come.
House Speaker Mike Johnson noted the aircraft’s significance to many military communities across the nation.
“The roar of a B-52 is a familiar sound to all of us in Bossier City, Shreveport, and the surrounding region, and reminds us daily of the courage and sacrifice of those in uniform,” Johnson posted.
“As more details emerge, we mourn alongside our military community and pray for the families, friends, and fellow service members grieving this devastating loss,” Johnson added.
The crash also caused damage to portions of the runway at Edwards Air Force Base, forcing officials to temporarily suspend flight operations while investigators and recovery crews secured the area.
Military officials have launched a formal accident investigation. While no cause has yet been identified, aviation experts note that test flights often involve unique operational conditions and that investigators will carefully examine aircraft systems, maintenance records, flight data, weather conditions, and crew communications.
Officials cautioned that a full investigation could take several months before definitive conclusions are reached.
California Gov. Gavin Newsom also extended condolences to the families of those lost while thanking first responders who responded to the scene.
Boeing confirmed that two of its employees were aboard the aircraft and said the company is fully cooperating with investigators.
“It is with great sadness that we confirm two Boeing employees were among those on board. We are in contact with their families and are offering support,” Boeing said.
Sen. Thom Tillis of North Carolina joined other leaders in honoring the victims.
“Susan and I are heartbroken by the tragic loss of eight lives in the B-52 crash at Edwards Air Force Base. Our hearts are with the families and loved ones of those lost, as well as the entire Edwards Air Force Base community. We honor their service to our nation and mourn their loss.”
As investigators work to determine what caused the accident, the nation is mourning the loss of eight Americans who were serving their country in support of a mission aimed at maintaining the technological edge of the U.S. military. Their sacrifice now becomes part of the long and storied history of Edwards Air Force Base, a location that has played a central role in some of America’s most important aviation achievements.

Massive Migrant Caravan Converges On U.S. For Democrat Midterm Victory

JUST IN: Pair Of Senior FBI Officials Arrested — It’s Damning

Pentagon Rolls Controversial Out Doomsday Strategy

NEW: Trump Vows To Prosecute His Own STAFF!

Trump Just Activated ‘Level 3’ — It’s Serious

Powerful Dem Senator Arrested 12 Days Before Midterms

Michelle Obama Public Disaster — Photos Explode Across D.C.

Feds Raid Ilhan Omar’s Home — Make Horrifying Discovery

Arrest Warrant Issued For POTUS Candidate — Horrifying Charges

Ocasio-Cortez QUITS — Stunning Moment On House Floor

Ilhan Omar’s Sister FLIPS — Blows Entire Case Wide Open!

‘I Will Go!’ — Ilhan Omar Drops Shock Announcement
-
 Economy7 months ago
Vance Leaves Meeting, Looks Straight Into Camera, Announces Stunning Arrest
-
 Economy7 months ago
Adam Schiff Facing 30 Years In Prison After Bank Records Leak
-
 Culture5 months ago
Michelle Obama Drops Nasty Bomb About ‘Useless’ Daughter
-
 Economy7 months ago
Supreme Curt Sides With Trump — He Can Remove The All
-
 Economy7 months ago
All Hell Breaks Loose On Fox When Jesse Watters Asks Fetterman One Question
-
 Economy5 months ago
Prayers Pour In After Fox Host Dies: ‘Senseless Murder’
-
 Border & Security3 months ago
Top Trump Admin And Wife Found Dead — Chilling Update Just Released
-
 Economy5 months ago
Pete Hegseth Just Confirmed Devastating Rumors